Rental Yield on Luxury Apartments in North Bangalore: The Real Numbers
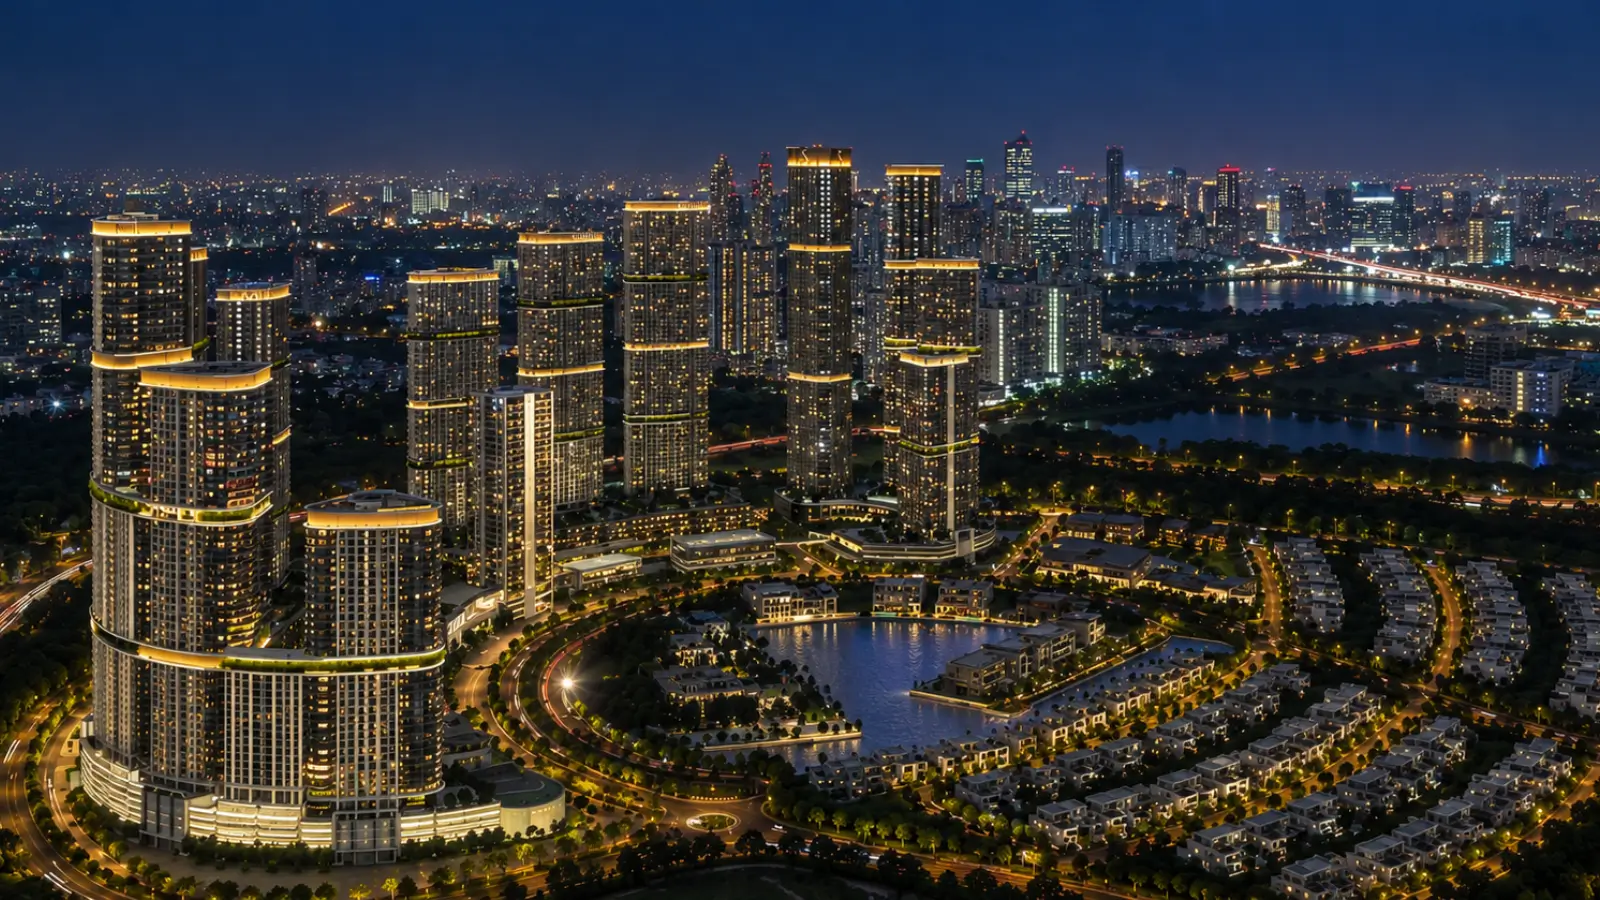
Rental yield is the most frequently quoted and most poorly understood number in Indian luxury real estate. Buyers are given a percentage without being...
Rental yield is the most frequently quoted and most poorly understood number in Indian luxury real estate. Buyers are given a percentage without being told whether it is gross or net, what furnishing standard it assumes, or whether it reflects achieved rents or asking rents. For an ultra-luxury residence in North Bangalore, the honest framework is narrower than most marketing suggests.
The working benchmark applied across A-class developer stock in this segment is 3.5 to 4 per cent of property cost annually for a semi-furnished residence, and 4 to 4.5 per cent for a furnished one. Expressed as a rate rather than an absolute, that translates to roughly 3.5 to 4 lakh rupees annually per crore of property cost semi-furnished, and 4 to 4.5 lakh per crore furnished. Monthly, the same figures are approximately 29,000 to 33,000 rupees per crore and 33,000 to 37,500 rupees per crore respectively.
These are gross figures and that distinction matters more here than in mainstream residential. A branded residence carries a service charge funding the management platform, concierge, security, facade cleaning and landscape upkeep, and that charge is materially higher than conventional apartment maintenance. It is an operating cost that sits directly against gross rent. Add property tax, periodic refurbishment between tenancies, and any letting or management commission, and the net figure lands meaningfully below the headline percentage. Anyone modelling this asset should compute net yield explicitly rather than adopting the gross band.
Yields at this price point are structurally lower than in the mid-market, and that is not a defect. Capital values in prime pockets rise faster than achievable rents, so the ratio compresses as you move up the price ladder. A residence at Embassy ONE North Tower is not primarily a yield instrument; it is a capital-preservation and use asset with an income component. Buyers who approach it as a cash-flow play will be disappointed by the arithmetic, while those treating income as a partial offset to holding cost will find it behaves as expected.
The demand side is what makes the upper end of the band achievable rather than theoretical. Tenants for this stock are senior expatriate management, C-suite executives on relocation packages, diplomatic and consular households, and corporates taking long-stay accommodation. These tenants pay for service, security and predictability rather than floor area alone, which is precisely what a Four Seasons managed residence supplies. Monthly rentals on the Bellary Road stretch have been reported across a wide band reaching approximately 7.5 lakh rupees, consistent with the top of this profile.
The practical instruction is to underwrite three numbers before purchase: the gross rent achievable for the specific residence at the specific furnishing standard, the annual service charge in writing, and a realistic vacancy assumption. A narrow tenant pool means voids can run longer than in mainstream stock, and a single extended vacancy erases a substantial share of an annual return at these percentages. This is general information rather than investment advice, and a specific purchase should be modelled with your own advisor.
Related reading: Semi-Furnished vs Furnished: How Furnishing Changes Your Rental Yield.
FAQs
What rental yield can a luxury apartment in North Bangalore achieve?
The working benchmark for A-class developer stock is 3.5 to 4 per cent of property cost annually semi-furnished and 4 to 4.5 per cent furnished. That equates to roughly 3.5 to 4 lakh rupees per crore annually semi-furnished, and 4 to 4.5 lakh per crore furnished.Are those yield figures gross or net?
Gross. A branded residence carries a service charge materially higher than conventional maintenance, and that sits directly against rent along with property tax, refurbishment between tenancies and any letting commission. Net yield lands meaningfully below the headline band.Why are ultra-luxury yields lower than mid-market yields?
Capital values in prime pockets rise faster than achievable rents, so the yield ratio compresses as prices climb. Ultra-luxury residences function primarily as capital-preservation and use assets with an income component rather than as cash-flow instruments.
Related Articles
Festive Season Home Buying in North Bangalore: Does the Timing Help?
Property enquiries in India rise sharply between September and November, and the industry has built a marketing season around it. Whether the timing...
Stamp Duty and Registration in Karnataka: A Complete Cost Guide
Transaction costs are the part of a property purchase buyers most often underestimate, and at ultra-luxury values the sums involved are substantial enough...
Bengaluru Metro Phase 3: The North Bangalore Property Impact
Metro expansion is the infrastructure story most likely to be oversold in Bengaluru property marketing, and the reason is that its effects are real but...
Karnataka RERA: How the Law Protects Luxury Homebuyers
The Real Estate (Regulation and Development) Act changed the balance of information between developer and buyer more than any other measure in Indian...